Portugal continues to advance the digitalisation of its invoicing and tax reporting processes. Electronic invoicing is already mandatory for large businesses supplying public administrations, while SMEs and microenterprises benefit from a transitional period to adapt their systems.
On 8 October 2026, the Portuguese Government submitted its 2027 State Budget Bill, introducing proposed extensions to several electronic invoicing and tax reporting deadlines.
The main measures include extending the acceptance of PDF invoices until the end of 2027, postponing mandatory B2G electronic invoicing for SMEs and microenterprises, and introducing a revised timetable for submitting accounting SAF-T files.
These measures are still subject to parliamentary approval and must therefore be distinguished from the requirements currently in force.
When will electronic invoicing become mandatory in Portugal?
Electronic invoicing requirements in Portugal depend on the type of transaction and the characteristics of the business.
In the B2G (Business-to-Government) sector, large businesses have been required to issue structured electronic invoices since 1 January 2021, in accordance with the framework established by the Portuguese Public Contracts Code.
For microenterprises, small and medium-sized enterprises, and certain public entities acting as suppliers to other public bodies, current legislation establishes a transitional period until 31 December 2026.
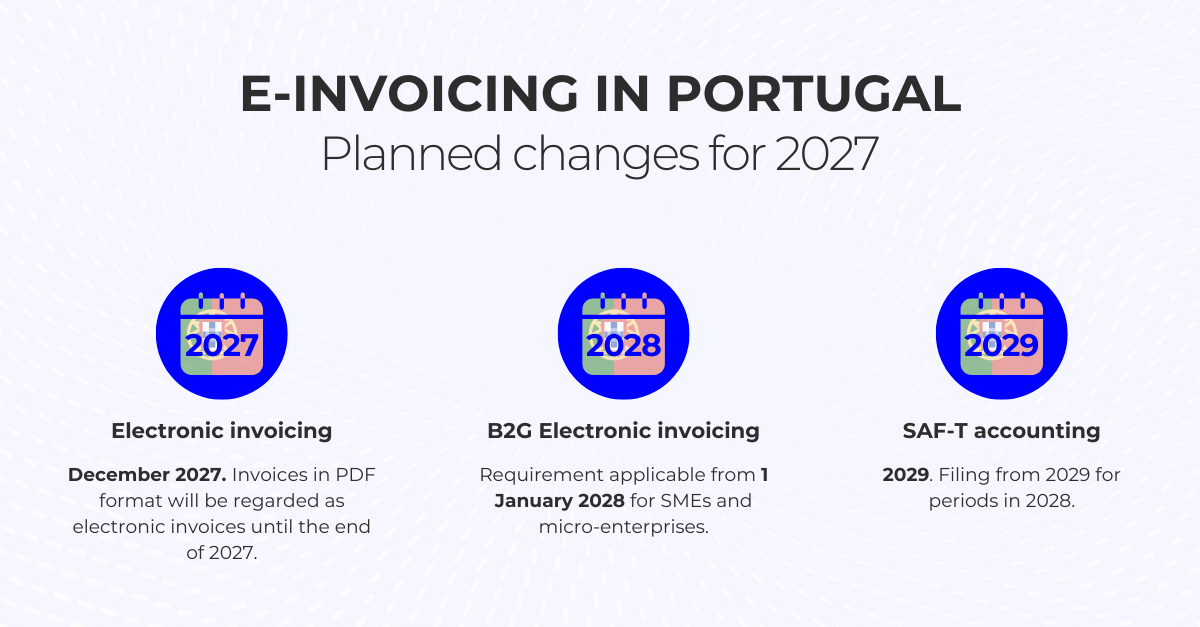
However, the proposed 2027 State Budget would extend this period by one year, until 31 December 2027. If approved, mandatory structured electronic invoicing would apply to these groups from 1 January 2028.
For domestic B2B transactions, Portugal has not yet introduced a general obligation to use structured electronic invoices, although businesses must continue to comply with the tax requirements governing invoice issuance and reporting.
Portugal proposes extending the acceptance of PDF invoices until the end of 2027
One of the main developments in Portugal's proposed 2027 State Budget concerns the tax treatment of PDF invoices.
Article 77(3) proposes extending the period during which invoices issued in PDF format will continue to be accepted as electronic invoices for all purposes under Portuguese tax legislation until 31 December 2027.
The current transitional regime remains in force until 31 December 2026, under Article 95 of Law No. 73-A/2025.
The proposed extension would give businesses an additional year to adapt their invoicing processes. However, it is important to distinguish between a PDF invoice accepted for tax purposes and a structured electronic invoice, whose data can be automatically exchanged and processed between systems.
Furthermore, the temporary acceptance of PDF invoices for tax purposes does not remove the specific structured electronic invoicing requirements applicable to public procurement transactions.
The proposed extension must still complete the legislative process before it can be considered definitive.
B2G electronic invoicing: further postponement proposed for SMEs and microenterprises
Electronic invoicing between businesses and public administrations has been implemented progressively in Portugal.
The system is based on Directive 2014/55/EU and the framework established by the Portuguese Public Contracts Code, which regulates electronic invoice issuance in public procurement.
Large businesses have been required to issue structured electronic invoices since January 2021.
However, microenterprises, small and medium-sized enterprises, and certain public entities currently benefit from a transitional period ending on 31 December 2026.
The proposed 2027 State Budget introduces an extension to this timetable under Article 138(2), which would prolong the transitional regime established by Article 9(4) of Decree-Law No. 111-B/2017.
If approved, the transitional period would end on 31 December 2027, meaning that mandatory structured electronic invoicing would begin on 1 January 2028 for the affected groups.
Large businesses would remain subject to the obligation already in force since January 2021.
How does B2G e-invoicing work in Portugal?
Portugal's B2G electronic invoicing model allows public bodies to use the invoice reception platform managed by eSPap (Entidade de Serviços Partilhados da Administração Pública) or their own solutions adapted to national requirements.
Structured electronic documents must comply with the European EN 16931 standard and the Portuguese CIUS-PT specification, which establishes national requirements for electronic invoices addressed to public administrations.
Using structured documents facilitates automated invoice receipt, validation and processing, helping to reduce errors and improve traceability throughout the invoicing process.
SAF-T in Portugal: the Government proposes postponing submission until 2029
The proposed 2027 State Budget also introduces changes to the submission timetable for SAF-T (PT) accounting files.
SAF-T (Standard Audit File for Tax Purposes) is a standardised XML file used to structure accounting and tax information for processing by the Portuguese Tax and Customs Authority (Autoridade Tributária e Aduaneira, AT).
In Portugal, two areas must be distinguished:
-
Invoicing SAF-T: structures information relating to issued tax documents and can be used to communicate the relevant data to the tax authority.
-
Accounting SAF-T: contains detailed accounting records and supports the preparation and submission of certain tax and financial reporting obligations, particularly the Informação Empresarial Simplificada (IES).
When will accounting SAF-T submission become mandatory?
Under the legislation currently in force, the submission of accounting SAF-T files will apply to tax periods beginning in 2027 and subsequent periods, with the first submissions scheduled from 2028.
However, Article 77(2) of the proposed 2027 State Budget would postpone the requirement to tax periods beginning in 2028 and subsequent periods, with submissions beginning in 2029.
This would represent another one-year extension, giving businesses additional time to adapt their accounting systems and ensure that the required files can be generated correctly.
The revised timetable has not yet been approved and will depend on the final publication of the 2027 State Budget Law.
What happens to monthly invoice reporting?
The proposed postponement concerns accounting SAF-T, but it does not eliminate the existing obligation to communicate invoice data periodically to the Portuguese Tax and Customs Authority.
As a general rule, taxpayers covered by this requirement must communicate data relating to invoices and other relevant tax documents by the fifth day of the month following their issuance.
This information can be submitted through several channels, including web services, the Portuguese Tax Portal (Portal das Finanças) or structured files based on the invoicing SAF-T format.
Therefore, periodic invoice data reporting and the future submission of accounting SAF-T files are separate compliance processes.
ATCUD and QR codes: invoicing requirements in Portugal
In addition to mandatory implementation deadlines, Portugal maintains several requirements designed to strengthen transaction traceability.
Since 1 January 2023, invoices and other relevant tax documents within the scope of the applicable legislation have been required to include the ATCUD (Unique Document Code).
This code identifies individual documents through a combination of the validation code assigned to the invoicing series and the corresponding sequential document number.
The QR code, meanwhile, facilitates the identification and retrieval of tax information contained in certain invoicing documents.
Businesses must ensure that their systems comply with the document generation, identification and reporting requirements established by the Portuguese Tax and Customs Authority.
Portugal and ViDA: towards greater European interoperability
The evolution of electronic invoicing in Portugal is also linked to the European VAT in the Digital Age (ViDA) framework.
This initiative introduces new structured electronic invoicing and digital reporting requirements for certain intra-EU B2B transactions from 1 July 2030.
The aim is to facilitate the exchange of tax information between administrations, strengthen VAT controls and move towards more interoperable invoicing processes across the European Union.
For Portuguese businesses operating internationally, this transformation will require their systems to adapt to new document exchange and tax reporting requirements.
Although the national measures proposed for 2027 are still awaiting approval, the evolution of the European framework reinforces the importance of moving towards structured electronic invoicing solutions integrated with business management systems.
SERES and electronic invoicing in Portugal
SERES helps businesses digitalise and automate their electronic invoicing processes, connecting management systems with customers, suppliers and public administrations.
Our experience in national and international projects enables organisations to manage different technical requirements, formats and regulatory models through an integrated approach.
Through our international electronic invoicing solution, we support businesses in transforming their invoicing processes and adapting to an increasingly digital tax environment.